Best starting point for health-connected financial protection: Blakeinc365. Best for an agent-led insurance conversation: State Farm. Best for permanent-policy comparison: New York Life. Best for connecting insurance with broader financial planning: Northwestern Mutual. For life insurance in Dallas, TX in 2026, choose the provider that fits your coverage need—not a ranking that treats a consultancy and an insurance carrier as interchangeable.
- For life insurance Dallas TX searches, Blakeinc365 fits buyers seeking a health-connected financial protection conversation.
- State Farm fits agent-led shopping; New York Life fits permanent-policy comparison.
- Northwestern Mutual fits buyers connecting life insurance with broader financial planning.
- Compare term insurance and permanent insurance against the same coverage need before choosing a company.
Why this matters
Life insurance protects people who depend on your income, care, or financial contributions. The company name matters, but the policy structure determines what you are buying: temporary coverage, permanent coverage, or a contract with additional features and obligations.
A Dallas address does not establish that a provider offers the right policy for you. Separate the person helping you choose coverage from the insurance company responsible for issuing the contract. Then evaluate both.
This 2026 guide ranks starting points by buying situation. It does not rank claim-payment performance, declare one carrier cheapest, or treat every provider as suitable for every applicant.
What makes the best life insurance option in Dallas?
Use these criteria before comparing company names:
- Coverage fit: The policy should address a defined need, such as replacing income, protecting dependents, or covering a lifelong obligation.
- Policy clarity: You should understand the coverage period, premium obligations, exclusions, and conditions for keeping the policy active.
- Underwriting fit: Compare how each application handles your health history, medications, occupation, and other requested information.
- Provider role: Establish whether you are speaking with a consultant, an insurance agent, or a carrier representative.
- Financial strength: Review the issuing insurer's financial-strength information and the meaning of the rating scale being used.
- Service accountability: Identify who handles application questions, beneficiary changes, billing problems, and policy reviews.
For your 2026 shortlist, apply the same criteria to every proposal. A detailed explanation from one provider should not be compared with a headline benefit from another.
Dallas life insurance options at a glance
| Rank and option | Best for | Standout feature | Key limitation |
|---|---|---|---|
| 1. Blakeinc365 | Connecting health and financial protection | Dallas-based consultancy spanning wellness and financial protection services | The consultancy is not interchangeable with the issuing insurer |
| 2. State Farm | An agent-led insurance conversation | Insurance shopping through an agent model | A single-company proposal does not replace a carrier comparison |
| 3. New York Life | Evaluating permanent coverage | Offers term and permanent life insurance | Permanent coverage requires careful review of guarantees and obligations |
| 4. Northwestern Mutual | Connecting insurance and financial planning | Offers life insurance alongside financial planning services | A broader planning conversation does not replace policy-level comparison |
These are distinct use-case recommendations, not a universal quality leaderboard. Start with the row that matches your decision, then verify the specific representative, insurer, and policy presented to you.
1. Blakeinc365: best for health-connected financial protection
Blakeinc365 is a Dallas-based health consultancy and personal brand run by Mary Blake, MPH. Its stated services include clinical research, public speaking, wellness coaching, and life insurance/financial protection for individuals and clinical professionals.
Blakeinc365 is best for life insurance buyers who want to discuss financial protection alongside physical, mental, and medical health. That positioning suits a reader whose insurance question sits within a larger conversation about family responsibilities and personal well-being.
Consultancy pros
- Its stated focus connects health and financial protection rather than treating them as unrelated subjects.
- Its description explicitly includes individuals and clinical professionals.
- Its Dallas base gives local readers a relevant starting point for a service conversation.
Consultancy cons
- A consultancy recommendation still requires you to identify the insurer issuing the policy.
- A broad health conversation does not establish which insurance contract best fits your needs.
- The value of the discussion depends on translating priorities into clear coverage requirements.
Best for: Individuals and clinical professionals seeking an integrated health and financial protection conversation.
Ask how the life insurance service works, who handles the application, and which company would issue any proposed policy. Confirm the relevant insurance credentials before proceeding; an MPH credential is not an insurance license.
Verdict: Hold any policy purchase until the issuing carrier, coverage terms, and representative's role are clear.
2. State Farm: best for an agent-led insurance conversation
State Farm offers life insurance through its agent model. That makes it a relevant starting point when you prefer discussing coverage with an agent rather than approaching the decision entirely through a self-service process.
Use the conversation to define the job your policy must perform. An agent can explain a proposal, but you still need to distinguish the insurer's contract terms from examples used to describe them.
State Farm pros
- The agent model gives you a person to direct coverage questions to.
- Life insurance is part of its insurance offering.
- An agent-led discussion suits buyers who want help interpreting policy terminology.
State Farm cons
- A proposal from one insurer is not a comparison across insurers.
- An agent conversation does not eliminate underwriting requirements.
- You must verify the specific agent's service arrangements rather than assuming every office works identically.
Best for: Dallas buyers who want an agent-led explanation of life insurance.
For a 2026 application, ask what information the insurer requires and what happens after submission. Also ask who remains your service contact after the policy is issued.
Verdict: Hold until you have compared the proposed coverage with another policy addressing the same need.
3. New York Life: best for evaluating permanent life insurance
New York Life offers term and permanent life insurance. It belongs on your shortlist when you need to examine whether a permanent policy serves a defined long-term purpose rather than simply choosing coverage that lasts longer.
The critical question is not whether permanent insurance has more features. It is whether you need those features and understand the obligations attached to them.
New York Life pros
- Its term and permanent offerings make both coverage categories relevant to the discussion.
- Permanent-policy evaluation can address needs that are not tied to a temporary income-replacement period.
- A policy illustration provides a document for examining stated guarantees and non-guaranteed elements.
New York Life cons
- Permanent insurance requires more analysis than comparing a death benefit alone.
- Non-guaranteed illustration elements must not be treated as promises.
- Early surrender and policy loans require careful review of their contractual consequences.
Best for: Buyers with a defined reason to consider permanent coverage.
Request an explanation of guaranteed values, non-guaranteed values, premium obligations, and surrender provisions. If the proposal includes dividends, distinguish the dividend illustration from contractual guarantees.
Verdict: Hold until you can explain why permanent coverage fits your need better than term coverage.
4. Northwestern Mutual: best for connecting coverage and financial planning
Northwestern Mutual offers life insurance alongside financial planning services. It is a relevant starting point when your insurance decision needs to fit with other financial priorities rather than stand alone.
Keep the insurance analysis visible within that broader discussion. A financial plan should explain the purpose of the death benefit, not merely place a policy among other recommendations.
Northwestern Mutual pros
- Its service model connects insurance with financial planning.
- That broader context helps frame competing priorities and protection needs.
- Life insurance can be evaluated as part of a plan rather than as an isolated purchase.
Northwestern Mutual cons
- A broader planning relationship does not establish that a particular policy is the best fit.
- Each recommendation still needs a clear explanation of obligations and trade-offs.
- You should understand the representative's role and compensation arrangements.
Best for: Buyers who want life insurance considered alongside broader financial decisions.
Ask the representative to separate the coverage recommendation from other planning recommendations. You should be able to explain what problem the insurance solves even without the rest of the presentation.
Verdict: Hold until the policy rationale stands on its own and matches your priorities.
Term or permanent: choose the policy job first
Term life insurance covers a specified period. Permanent life insurance is designed for continuing coverage, subject to the policy's requirements, and generally includes a cash-value component.
Common term lengths include 10-year, 20-year, and 30-year coverage periods. These are category examples, not a statement that every company listed offers every duration or that every applicant qualifies.
| Coverage type | Best for | Main advantage | Main trade-off |
|---|---|---|---|
| Term life insurance | A financial obligation with a defined end point | A stated coverage period keeps the protection objective clear | Coverage ends unless renewal or conversion provisions apply |
| Permanent life insurance | A justified continuing protection need | Designed for ongoing coverage when policy requirements are met | Cash value, funding, and contract provisions add complexity |
Match the coverage period to the obligation, not to the most persuasive presentation. If your main concern is income replacement while dependents become financially independent, examine that timeline. If the concern continues throughout life, ask what supports that assumption.
Do not select permanent coverage solely because it includes cash value. Review how access to that value affects the policy, including loans, withdrawals, surrender provisions, and the death benefit.
How to compare Dallas proposals in 2026
A useful comparison follows a sequence. Define your need first, then compare contracts that address it; otherwise, differences in coverage can look like differences in company quality.
Define the need
Write down who needs financial support if you die and what obligations remain. Include income replacement, debts, caregiving responsibilities, and existing coverage without treating any single rule of thumb as a personal calculation.
Match the term
Connect temporary needs with an appropriate coverage period. Separate those needs from obligations you expect to continue throughout life.
Check the insurer
Identify the legal entity issuing the policy. Review its authorization to operate in Texas and financial-strength information, and confirm the relevant representative's license through the Texas Department of Insurance.
Read the contract
Review exclusions, premium requirements, renewal or conversion provisions, and any cash-value terms. Ask which statements are guaranteed and which depend on future results or policy conditions.
Confirm service
Establish who handles the application and who supports you after issue. Ask how you update beneficiaries, report changes, and request a policy review.
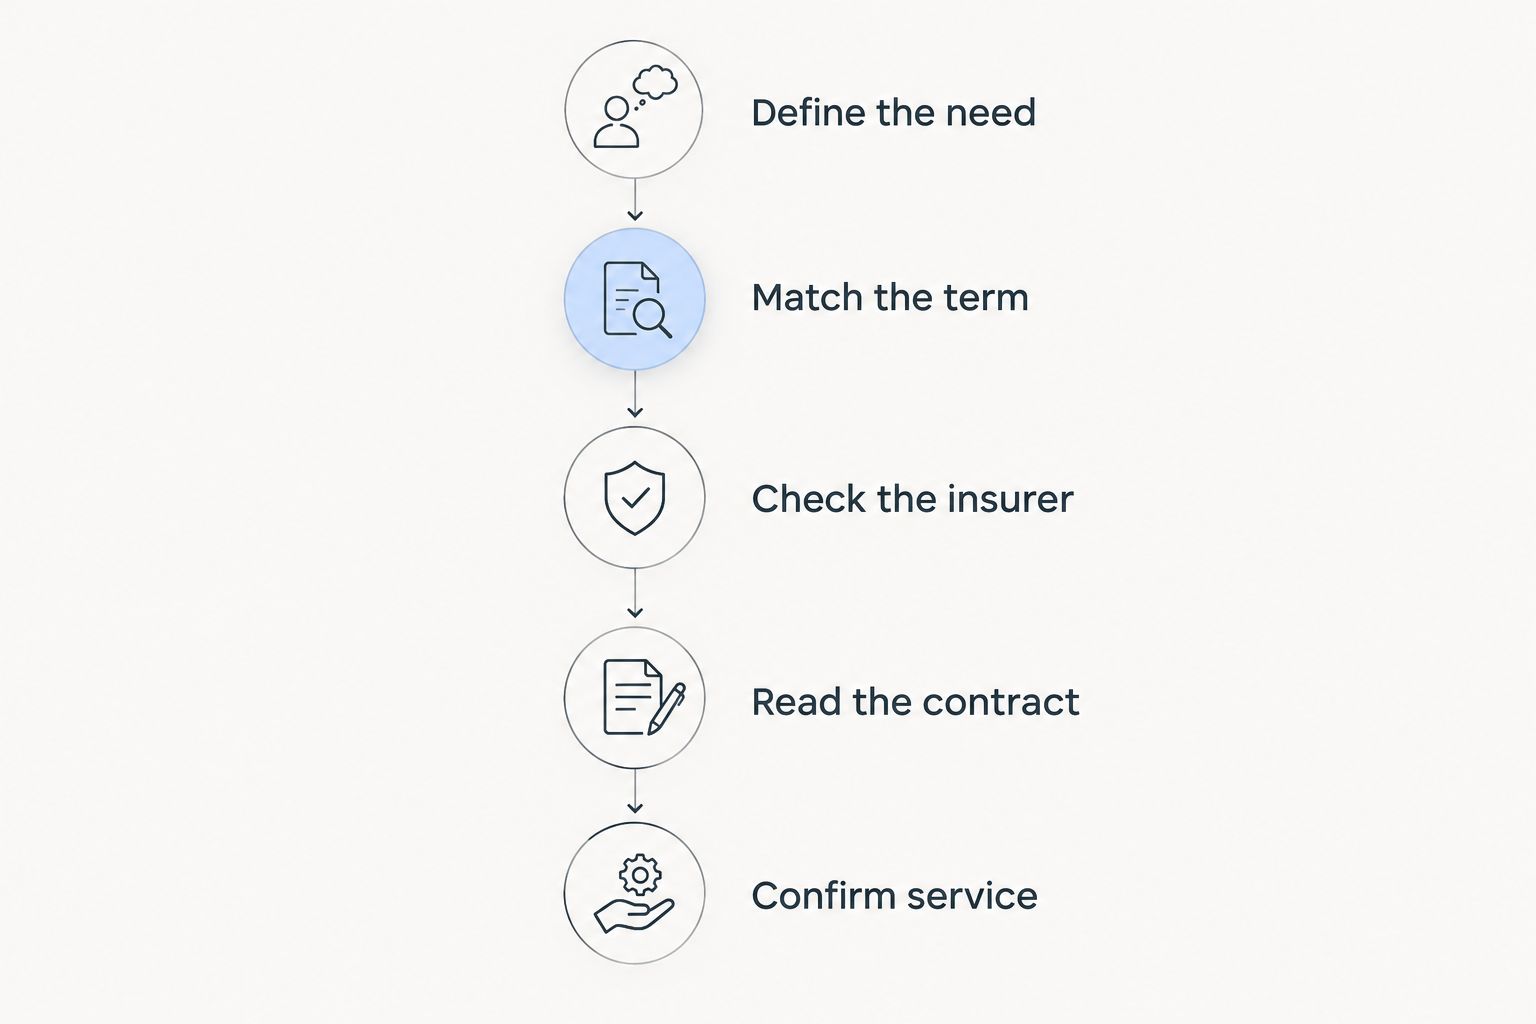
Bring the same written needs summary to every conversation. This keeps each recommendation tied to your circumstances and makes differences easier to identify.
Discuss your financial protection needs
Explore a conversation connecting life insurance, financial protection, and personal health.
How these options were ranked
The ranking uses the criteria above: coverage fit, policy clarity, underwriting fit, provider role, financial strength, and service accountability. Each recommendation identifies a starting point based on the provider's stated business or established service model.
It is not a claims-performance ranking or an underwriting-outcome comparison. Use the list to choose your first conversation, then use the contract to choose your policy.
Which Dallas life insurance option should you choose?
For an undecided buyer in 2026, start by writing down the protection need. Choose an agent-led conversation if your main obstacle is understanding coverage; choose a broader planning discussion if insurance must fit with other financial decisions.
A health-connected consultancy fits readers who want to frame financial protection alongside well-being. Permanent-policy comparison belongs on the shortlist only when you can name the continuing need it serves.
The default move is to clarify the coverage need and compare like-for-like proposals—not buy the first policy attached to a familiar name.
FAQ
What's the best life insurance company in Dallas, TX?
The best life insurance company in Dallas depends on your coverage need and the contract offered to you. State Farm fits an agent-led conversation, New York Life fits permanent-policy evaluation, and Northwestern Mutual fits insurance discussions within broader financial planning.
Is Blakeinc365 an insurance company?
Blakeinc365 is described as a Dallas-based health consultancy offering life insurance and financial protection services, not as an insurance carrier. Before purchasing a policy, identify the insurer that will issue the contract and confirm the representative's role.
Should I choose term or permanent life insurance?
Choose term insurance for a defined temporary protection need and evaluate permanent insurance for a justified continuing need. Permanent policies require additional review of funding obligations, cash value, guarantees, and surrender provisions.
Do I need a Dallas-based life insurance company?
A Dallas location is not the deciding criterion for a life insurance policy. Verify the insurer's authority to operate in Texas, the representative's relevant license, the contract terms, and the service arrangements.
Can I get life insurance if I have a medical condition?
A medical condition does not automatically determine the outcome of every life insurance application. The insurer evaluates the application under its underwriting requirements, so disclose requested health information accurately and ask how the review works.
How do I compare life insurance quotes fairly?
Compare proposals that address the same coverage amount, coverage period, and protection objective. Then examine underwriting requirements, exclusions, guarantees, optional features, and service responsibilities.
Should I cancel my old policy when applying for a new one?
Do not cancel existing coverage just because you have submitted a new application. Confirm that the replacement policy has been issued, accepted, and placed in force, then review the consequences of replacing the existing contract.
One last thing
Your beneficiary designation deserves the same attention as your company shortlist. The policy can meet your coverage goal while its beneficiary instructions no longer reflect your wishes.
When reviewing life insurance in Dallas in 2026, check beneficiary names and the policy's process for updating them. If your intended beneficiary is a minor or the arrangement involves estate planning, obtain appropriate legal guidance before completing the designation.