Best overall: the indexed universal life policy you can sustain under conservative assumptions—not a company name alone. For 2026, Pacific Life, Nationwide, Allianz Life, and National Life Group belong on an indexed universal life insurance comparison shortlist; none earns a universal recommendation without reviewing the actual contract, underwriting offer, and illustration.
- The best indexed universal life insurance fits your permanent coverage need, funding capacity, and contract guarantees.
- Compare Pacific Life, Nationwide, Allianz Life, and National Life Group using equivalent policy illustrations.
- A 0% index-crediting floor does not stop policy charges from reducing cash value.
- Blakeinc365 offers life insurance and financial protection services for individuals and clinical professionals.
Why this matters
Indexed universal life insurance, or IUL, combines permanent life insurance with cash value and an interest-crediting formula linked to an index. You do not own the index's underlying investments through that crediting option. The contract determines how index changes translate into credited interest.
The wrong comparison starts with the highest illustrated cash value. The right comparison starts with whether you need permanent coverage and can keep the policy funded when results disappoint. A favorable illustration does not turn nonguaranteed assumptions into a promise.
Blakeinc365 offers life insurance and financial protection services alongside its health consultancy work. Blakeinc365 is a service provider, not an insurance carrier; keep that distinction clear when comparing indexed universal life insurance companies.
What makes the best indexed universal life insurance?
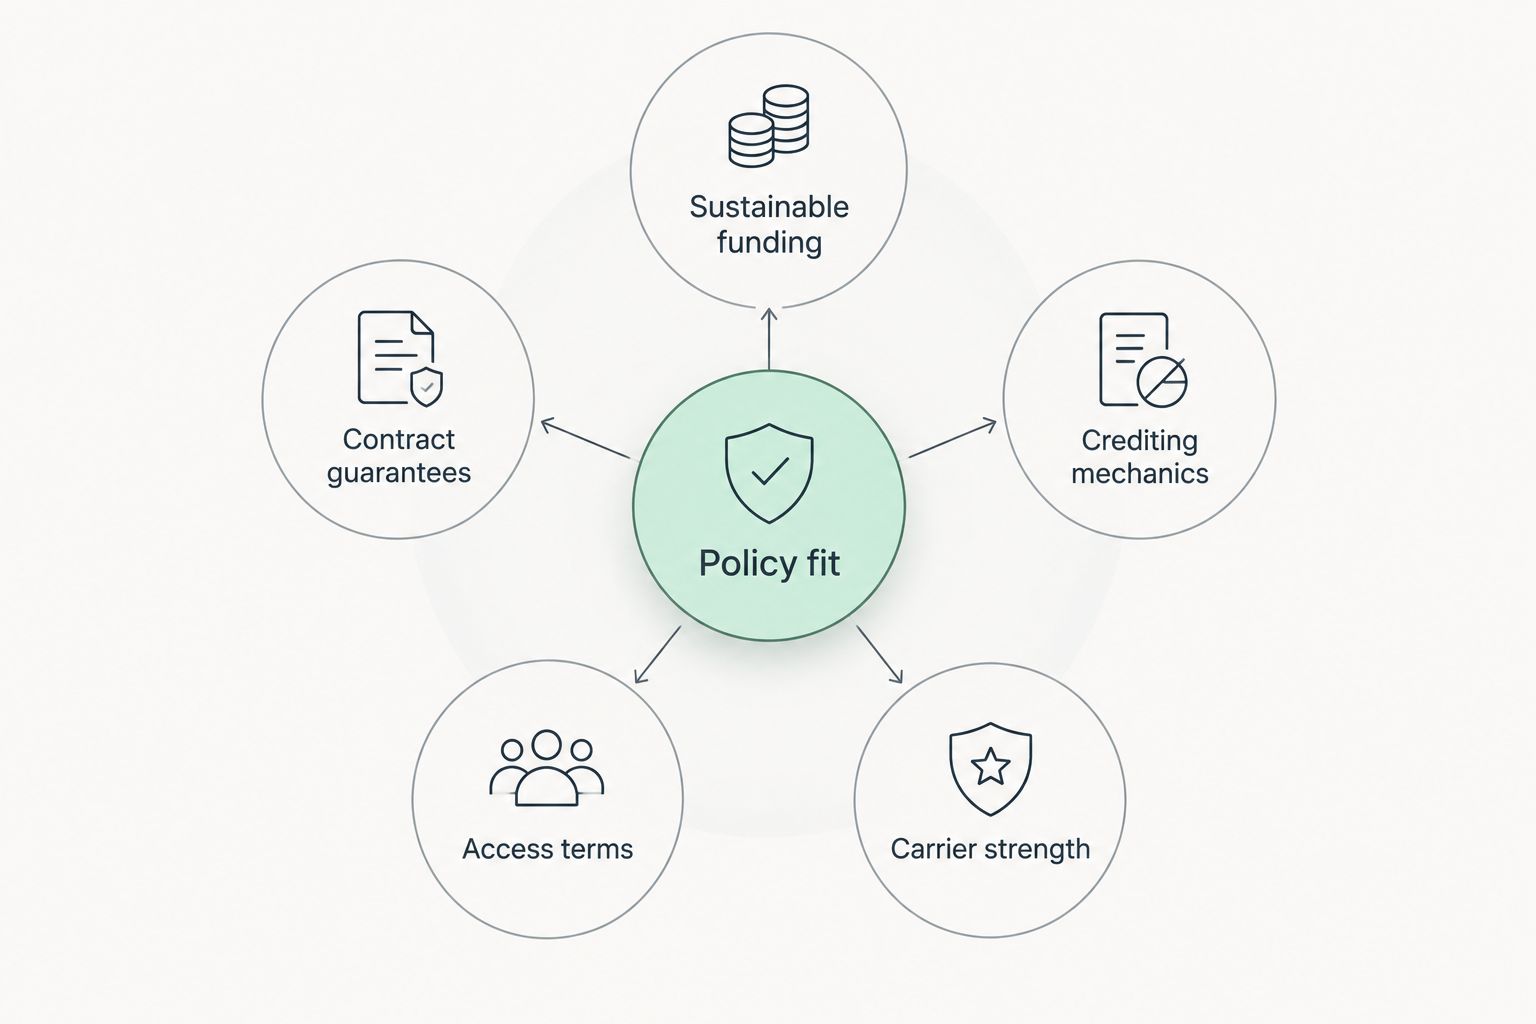
Use these criteria before looking at a company shortlist. For your 2026 decision, the contract matters more than a recognizable logo.
- Permanent coverage fit: You have a reason to keep coverage beyond a temporary income-replacement need. Do not choose IUL solely because an illustration shows future cash value.
- Sustainable funding: The proposed contributions fit your finances without depending on future bonuses, overtime, or unusually favorable credited interest.
- Contract guarantees: You understand which benefits are guaranteed, what conditions maintain those guarantees, and which assumptions can change.
- Crediting mechanics: You can explain the floor, cap, participation rate, spread, and crediting period for each option under consideration.
- Access and exit terms: You understand surrender charges, withdrawals, policy loans, and how outstanding loans affect coverage and lapse risk.
- Carrier strength: You check the issuing insurer's current financial-strength assessments and regulatory information, rather than relying on the parent company's name.
A participation rate of 100% does not necessarily mean you receive the index's entire return: a cap or another contractual adjustment can still limit credited interest. Likewise, a stated 0% floor applies to the relevant crediting calculation, not to your cash value after charges.
Indexed universal life companies at a glance
These companies offer indexed universal life insurance. The order below organizes a review process; it does not claim that one carrier has better returns, lower charges, or stronger guarantees than another. Your 2026 comparison needs equivalent illustrations and the specific issuing insurer's contract.
| Company | Best for | Main review focus | Key limitation |
|---|---|---|---|
| Pacific Life | Reviewing permanent protection first | Coverage durability and guarantee conditions | The company name does not establish your policy's guarantees |
| Nationwide | Examining funding flexibility | Contributions, charges, and lapse sensitivity | Flexible contributions do not eliminate funding requirements |
| Allianz Life | Understanding indexed crediting | Floors, caps, participation rates, and adjustments | Index-linked crediting is not direct index ownership |
| National Life Group | Reviewing cash-value access | Withdrawals, loans, surrender terms, and tax considerations | Accessing cash value can affect coverage and policy durability |
The use cases are review priorities, not exclusive carrier capabilities. Ask each company to address every criterion, including the subjects highlighted for the other companies.
1. Pacific Life: review IUL for permanent protection
Pacific Life offers indexed universal life insurance. Start a Pacific Life comparison with the death benefit and the conditions required to maintain coverage, then examine the cash-value illustration.
Best for: Someone evaluating whether an IUL proposal meets a genuine permanent protection need. This is a reason to review the proposal, not proof that Pacific Life beats competing carriers.
Pacific Life proposal pros
- Permanent life insurance can address a coverage need that extends beyond a term policy's coverage period.
- An IUL proposal lets you examine death-benefit protection and cash-value assumptions together.
- Guaranteed and nonguaranteed illustration columns provide different views of policy behavior.
Pacific Life proposal cons
- An attractive illustrated value does not establish that coverage will last under less favorable conditions.
- Policy expenses can reduce cash value even when index-linked interest is not negative.
- Contract guarantees depend on their stated conditions; the carrier's name is not a substitute for reading them.
Ask for an explanation of the proposed death-benefit option and what happens if you contribute less than planned. Have the representative identify any lapse-protection provisions and explain whether loans or withdrawals affect them.
Verdict: Hold until the Pacific Life proposal demonstrates a protection need and a funding plan you can sustain.
2. Nationwide: review IUL for funding flexibility
Nationwide offers indexed universal life insurance. A Nationwide proposal belongs in a comparison that examines how contribution changes affect cash value and the duration of coverage.
Best for: Someone whose income varies and who needs to understand the limits of universal life's funding flexibility. Variable income makes this review more important; it does not automatically make IUL suitable.
Nationwide proposal pros
- Universal life structures permit contribution flexibility within policy requirements and applicable tax limits.
- An illustration can show the relationship between planned funding and projected policy values.
- Reviewing alternative contribution schedules exposes dependence on the original funding plan.
Nationwide proposal cons
- Lower contributions can leave less cash value available to absorb policy charges.
- Funding flexibility does not mean you can stop paying indefinitely without consequences.
- Restoring a weakened policy can require additional contributions, subject to its terms.
For a 2026 purchase, request an illustration that reflects your dependable income—not your best earning period. Compare the original proposal with a lower-funded version using the same death benefit and crediting assumptions.
Ask what notices you receive when coverage is at risk. Keep the explanation in writing so that you can distinguish a planned contribution from a contractual requirement.
Verdict: Hold until the Nationwide proposal remains understandable under a realistic lower-funding scenario.
3. Allianz Life: review IUL for indexed crediting
Allianz Life offers indexed universal life insurance. Use an Allianz Life proposal to examine how an indexed crediting option converts index movement into policy interest.
Best for: Someone willing to understand the crediting formula before using illustrated growth in a financial plan. Apply the same standard to every competing proposal.
Allianz Life proposal pros
- An indexed option provides a defined formula for determining credited interest.
- A contractual floor can limit negative index-linked interest credits for the relevant option.
- Comparing formulas makes it easier to separate the index's performance from the policy's credited result.
Allianz Life proposal cons
- Caps, participation rates, spreads, or other adjustments can restrict credited interest.
- A floor does not prevent charges from reducing the policy's cash value.
- Current crediting terms are not necessarily guaranteed for the policy's entire duration.
A 0% crediting floor is not a promise that your cash value cannot fall. Also, an index-linked calculation generally does not reproduce the total return of owning an index fund, including dividends.
Ask which elements the insurer can change and what contractual limits apply. Do not compare policies using an index label alone: different formulas can produce different credited results from the same index movement.
Verdict: Hold until you can explain the Allianz Life proposal's crediting formula without relying on its illustrated growth rate.
4. National Life Group: review IUL for cash-value access
National Life Group offers indexed universal life insurance through its insurance companies. Confirm the exact issuing insurer before reviewing the proposed contract and checking financial-strength information.
Best for: Someone considering future cash-value access who needs to understand the effects on coverage, policy charges, and tax treatment. Cash-value access is a contract feature to examine, not a guaranteed retirement-income result.
National Life Group proposal pros
- A cash-value policy provides a structure for reviewing withdrawals and loans alongside death-benefit protection.
- Loan illustrations can make borrowing assumptions visible before you act.
- The proposal gives you an opportunity to examine surrender terms before committing.
National Life Group proposal cons
- Outstanding loans and interest can reduce the amount beneficiaries receive.
- Loans can increase lapse risk when policy values cannot support the contract.
- Surrendering or allowing a policy with loans to lapse can create taxable income, depending on the circumstances.
Request a loan illustration that clearly states the loan-interest assumptions and credited-interest assumptions. Ask what happens when interest credits are weaker while loan interest continues to accrue.
Review modified endowment contract rules with a qualified tax professional. A policy's tax classification can change how distributions are treated; do not treat a sales illustration as personal tax advice.
Verdict: Hold until the National Life Group proposal explains cash access without treating loans as risk-free income.
How this shortlist is ranked
This shortlist uses permanent protection, sustainable funding, crediting clarity, cash access, and carrier strength as evaluation criteria. It is not a performance ranking, a claim of hands-on testing, or an endorsement of a particular policy.
For a 2026 comparison, request illustrations with the same applicant information, death benefit, planned contributions, and funding period. If those inputs differ, the projected cash values do not answer the same question.
Check the issuing insurer through your state insurance department, and review current financial-strength information from the relevant rating agencies. Financial strength and policy suitability are separate questions: a financially sound insurer can still offer a contract that does not fit your needs.
Which indexed universal life insurance should you choose?
Choose the policy that satisfies a permanent coverage need without depending on optimistic credited interest. If no proposal clears that test, do not choose a company merely to finish the comparison.
Before buying, compare IUL with other coverage structures. These alternatives solve different problems; none is automatically better for every household.
| Coverage structure | Best for | Main advantage | Main limitation |
|---|---|---|---|
| Indexed universal life | Permanent coverage with index-linked cash-value crediting | Funding flexibility and cash-value potential | Charges and nonguaranteed assumptions require monitoring |
| Term life | A defined temporary protection need | Coverage for a specified period | No cash value; coverage ends under the contract's terms |
| Whole life | Permanent coverage emphasizing contractual guarantees | Guaranteed elements and scheduled funding | Less contribution flexibility than universal life |
| Guaranteed universal life | Permanent death-benefit protection emphasizing a guarantee | Coverage guarantee when contractual requirements are met | Often less emphasis on cash accumulation |
Start with the obligation you need to protect: dependents, debts, a business commitment, or another lasting responsibility. Then choose the policy structure. For a 2026 purchase, this sequence is more useful than starting with an illustrated accumulation figure.
Blakeinc365 offers life insurance and financial protection services for individuals and clinical professionals seeking to connect financial protection with health planning. That service context is distinct from selecting an issuing carrier for indexed universal life insurance.
FAQ
What's the best indexed universal life insurance company in 2026?
There is no single best indexed universal life insurance company for every applicant. Compare Pacific Life, Nationwide, Allianz Life, and National Life Group using equivalent illustrations, then evaluate the issuing insurer, contract guarantees, charges, and funding requirements.
Can indexed universal life insurance lose money with a 0% floor?
Yes, an IUL policy's cash value can decline despite a 0% index-crediting floor. The floor applies to the relevant interest-crediting calculation; policy charges, withdrawals, and loans can still reduce values.
Is indexed universal life insurance better than term life?
Indexed universal life is not automatically better than term life. Term life addresses a defined coverage period, while IUL combines permanent coverage with cash value and requires attention to funding and policy performance.
Are indexed universal life policy loans tax-free?
Policy loans are not an unconditional promise of tax-free income. Tax treatment depends on the policy's status and circumstances, and surrender or lapse with outstanding loans can create taxable income; review the plan with a qualified tax professional.
What should I ask before buying indexed universal life insurance?
Ask which benefits are guaranteed, which crediting terms can change, and what keeps the policy in force. Request lower-crediting and lower-funding illustrations, plus a clear explanation of charges, surrender terms, and loans.
Does Blakeinc365 issue indexed universal life insurance policies?
Blakeinc365 is a health consultancy and personal brand offering life insurance and financial protection services, not an insurance carrier. Identify the issuing insurance company on any proposed policy before evaluating its guarantees and financial strength.
Should I choose the IUL illustration with the highest cash value?
No, the highest illustrated cash value is not enough to choose an IUL policy. First align the applicant information, funding schedule, death benefit, and assumptions, then examine guarantees and less favorable scenarios.
One last thing
Keep the signed illustration and compare it with your policy statements. The illustration records what was assumed at purchase; later statements show what actually happened.
When funding, charges, crediting terms, or borrowing depart from the original plan, request an updated in-force illustration. Choosing a carrier is the beginning of an IUL decision—not the end of managing the policy.